4 Mins
Written by: Beth Anderson
Manager, Corporate Tax
Last reviewed: 12 October 2026Many businesses assume they can identify qualifying R&D projects years later and submit a retrospective claim.
That’s no longer always the case.
HMRC’s Claim Notification Form (CNF) requirements mean some companies must notify HMRC of their intention to claim R&D tax relief before submitting their Corporation Tax return. Miss the deadline and a valid claim could be lost before it’s ever submitted.
Do You Need to Notify HMRC Before Claiming R&D Tax Relief?
You may need to submit a Claim Notification Form if:
- You’re making your first R&D tax relief claim.
- You haven’t made a valid R&D claim within HMRC’s three-year lookback period.
- Historic claims do not satisfy the transitional rules introduced alongside the new regime.
As a result, businesses can no longer assume they’ll be able to revisit qualifying projects years later and make a successful claim.
Why This Matters
Historically, many businesses identified R&D activity after their year-end and then worked with advisers to prepare a claim retrospectively.
While Corporation Tax returns can still be amended within the usual time limits, a missed Claim Notification deadline cannot normally be fixed later.
This means a business could carry out genuine qualifying R&D work, incur significant costs and still be unable to claim relief if the notification requirements were not met.
The risk is no longer simply whether an activity qualifies. It’s whether the necessary steps have been taken early enough.
Which Businesses Are Most Likely to Be Affected?
First-Time Claimants
If your business has never claimed R&D tax relief before, you will need to submit a Claim Notification Form before making a claim.
Businesses That Haven’t Claimed Recently
Even if you’ve claimed in the past, a notification may still be required if you haven’t made a valid claim within the relevant lookback period.
This often catches businesses that only claim occasionally or have had gaps between innovation projects.
Companies Relying on Historic Claims
Some businesses assume a previous claim automatically removes the need for notification.
However, transitional rules mean certain historic claims may be disregarded when assessing whether a Claim Notification Form is required.
A Simple Example
Imagine a company develops a new software platform and incurs qualifying R&D expenditure during the year.
Management assumes they can review the project retrospectively when preparing their Corporation Tax return and claim the relief at that stage.
However, they later discover that a Claim Notification Form was required and the deadline has already passed.
Despite having a potentially valid R&D claim, the business may lose access to the relief because the notification requirement wasn’t met on time.
What Should Businesses Do?
To reduce the risk of missing out on valuable relief, businesses should consider R&D tax claims much earlier in the process.
Practical steps include:
- Identifying potential R&D projects throughout the year rather than after year-end.
- Reviewing whether a Claim Notification Form may be required.
- Keeping records of previous R&D claims and submission dates.
- Speaking to an adviser before key filing deadlines if there is any uncertainty.
Taking action early can help avoid discovering an issue when it’s already too late to correct.
Do You Need to Submit a Claim Notification Form?
The rules can seem complex, particularly if your business has claimed R&D tax relief before.
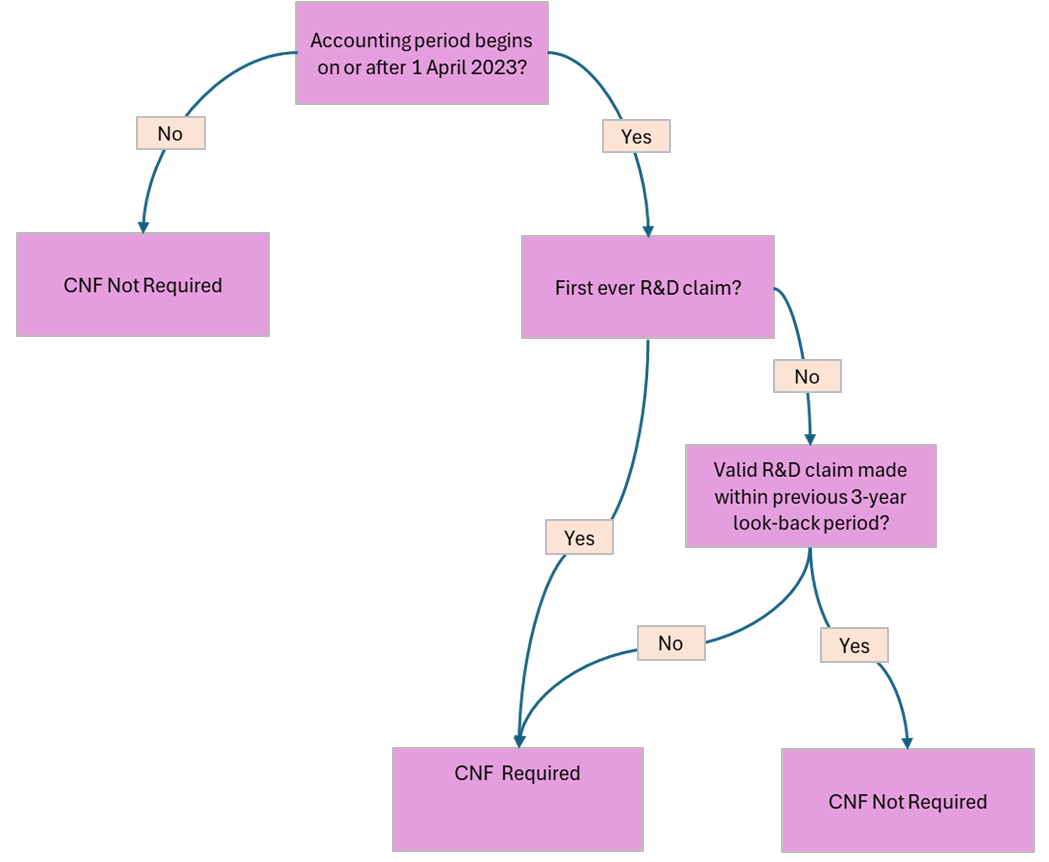
As a general guide:
- If your accounting period began before 1 April 2023, a Claim Notification Form is not typically required.
- If you’re making your first R&D tax relief claim, a Claim Notification Form will be required.
- If you’ve claimed before, whether a Claim Notification Form is needed will depend on when previous claims were made and whether they satisfy HMRC’s lookback rules.
The flowchart below provides a simplified overview of when a Claim Notification Form may be required.
Don’t Let an Administrative Deadline Prevent a Valid Claim
Many businesses still believe R&D tax relief can be dealt with retrospectively at any point within the Corporation Tax amendment window.
However, Claim Notification requirements mean that’s no longer always true.
If your business is developing new products, creating software, improving processes or investing in innovation, it’s important to establish whether a Claim Notification Form is required before filing deadlines approach.
Otherwise, valuable tax relief could be lost before a claim is ever submitted.
If you’re unsure whether your business needs to submit a Claim Notification Form, our Corporate Tax specialists can review your position and help ensure potential R&D claims aren’t missed.
FAQs About R&D Claim Notifications
A Claim Notification Form is a submission to HMRC that notifies them of your intention to make an R&D tax relief claim. If the requirement applies and the form is not submitted by the deadline, you may be unable to make a valid claim.
No. A Claim Notification Form is generally required for first-time claimants and some businesses that have not made a recent valid R&D claim. Whether a notification is required depends on your circumstances and claim history.
In some situations, Corporation Tax returns can still be amended retrospectively. However, if a Claim Notification Form was required and the deadline was missed, this cannot usually be corrected later.
No. Certain historic claims may be disregarded under transitional rules. This means some businesses may still need to submit a Claim Notification Form even if they have claimed R&D relief previously.
If your business was required to submit a Claim Notification Form and the deadline is missed, HMRC may reject a subsequent R&D tax relief claim, even where the underlying activity would otherwise qualify for relief.